What's covered on this page
- What Counts as a Shophouse Sale or Purchase in Singapore
- Foreign Ownership and Commercial-Use Rules Explained
- Selling and Buying at the Same Time Without Two Mortgages
- Conservation Status and Renovation Limits to Check First
- When a Shophouse Purchase Isn't the Right Fit
What Counts as a Shophouse Sale or Purchase in Singapore
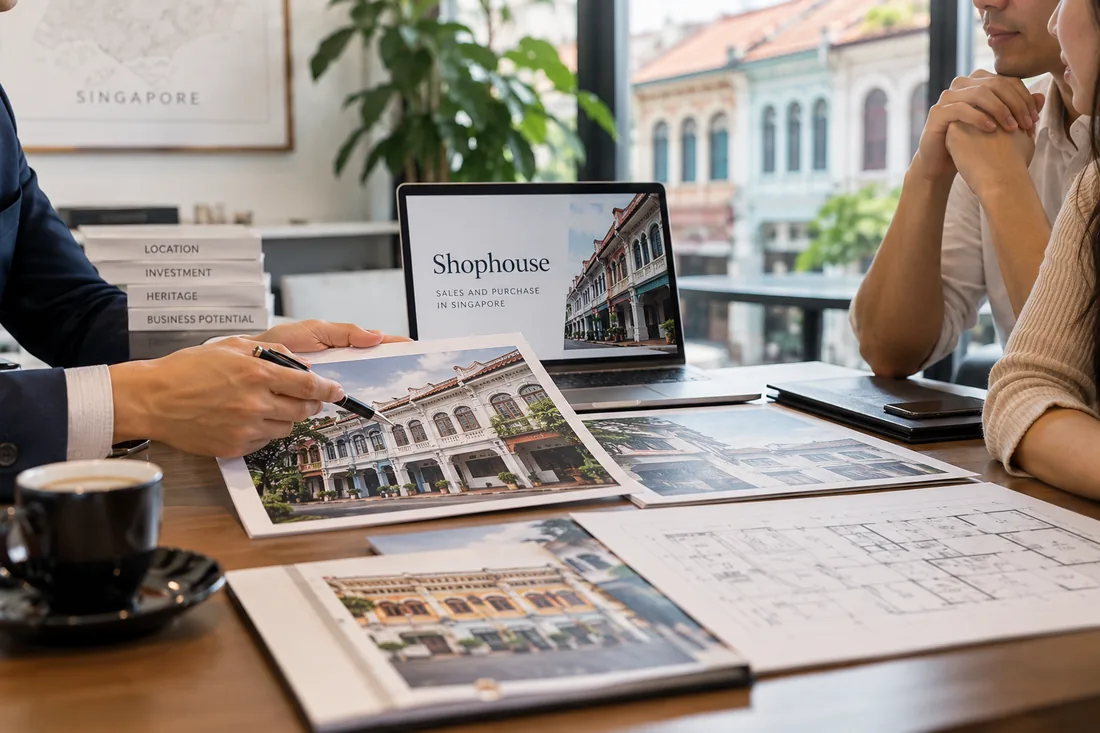
Not all shophouses are the same deal. A conservation shophouse, a commercial-zoned unit, and a mixed landed shophouse each come with different rules on use, tenure, and financing.
Most first-time shophouse buyers don't realise this. The word "shophouse" on a listing doesn't tell you much. It could be a pre-1965 conservation unit under strict facade rules, a plain commercial-zoned building, or a rarer mixed landed shophouse.
- Conservation shophouse - protected under URA guidelines, usually pre-1965, facade can't be altered without approval
- Commercial shophouse - zoned for retail, F&B, or office use, no residential use allowed unless approved
- Mixed landed shophouse - rare, allows residential use on upper floors while ground floor stays commercial
- Tenure split - some are freehold, others 99-year leasehold, changing how banks assess the loan
Zoning is the part that trips people up most. A shophouse zoned purely commercial can't be used as a home, no matter how nice the upper floor looks.
Foreign Ownership and Commercial-Use Rules Explained
First question I get from foreign buyers is simple. Can I even buy this? Good news, usually yes. A shophouse is zoned commercial or mixed use, not purely residential, so it sits outside the Singapore Land Authority approval rule that applies to landed houses.
- URA zoning on the specific plot decides whether upper floors can be residential, office, or must stay commercial
- Conservation status can limit renovation and change of use
- Ground floor commercial use is often required regardless of who owns the building
- Company purchases may face different loan and stamp duty treatment
The question isn't can you buy it, it's what you're allowed to do with it after. Check first, fall in love later.
Selling and Buying at the Same Time Without Two Mortgages
Shophouse deals move slower than condo deals. Legal completion usually runs 10 to 12 weeks from the Option to Purchase. That gap is where owners get nervous about holding two properties at once.
- Get your shophouse valued and priced against recent comparable transactions
- Market and secure a buyer, negotiate the Option to Purchase and completion date
- Use the completion window to shop for your next property with confirmed sale proceeds
- Align both completion dates so you move once, not twice
We've helped over 40 clients move through this exact sequence without juggling two mortgages.
Conservation Status and Renovation Limits to Check First
Most shophouses left in Singapore sit inside a conservation area. A unit in Joo Chiat or Kampong Glam might look like it's yours to gut and redo, but it isn't - the facade, five-foot way, roof form, and often the internal timber staircase fall under URA conservation guidelines.
- Whether the front facade and window details are protected
- If the roof structure and tiles need to match original materials
- Whether internal walls can be moved or are load bearing and protected
- If a change of use needs separate approval
Ask for the conservation status and any past renovation approvals before you commit, not after.
When a Shophouse Purchase Isn't the Right Fit
If you need a bank loan that behaves like a normal home loan, a shophouse might frustrate you. Most shophouses are zoned commercial or commercial with residential use above, and banks treat that differently.
- Buyers who need to move in within weeks - conservation approvals and commercial loan processing rarely move that fast
- Buyers stretching their entire budget on the purchase price alone
- Buyers who haven't spoken to a bank yet about commercial mortgage eligibility
None of this means shophouses are risky. It just means they're specific.